
(Bloomberg) — Oil eased, cooling the rally that pushed prices up by almost 5% on Wednesday.
Futures in New York fell below $63 a barrel on the back of the longest run of gains in more than a month.
Signs of a stronger U. S. market are abounding. The number of miles driven on the country’s interstates rose versus the same period in 2019 for the first time since the pandemic began.
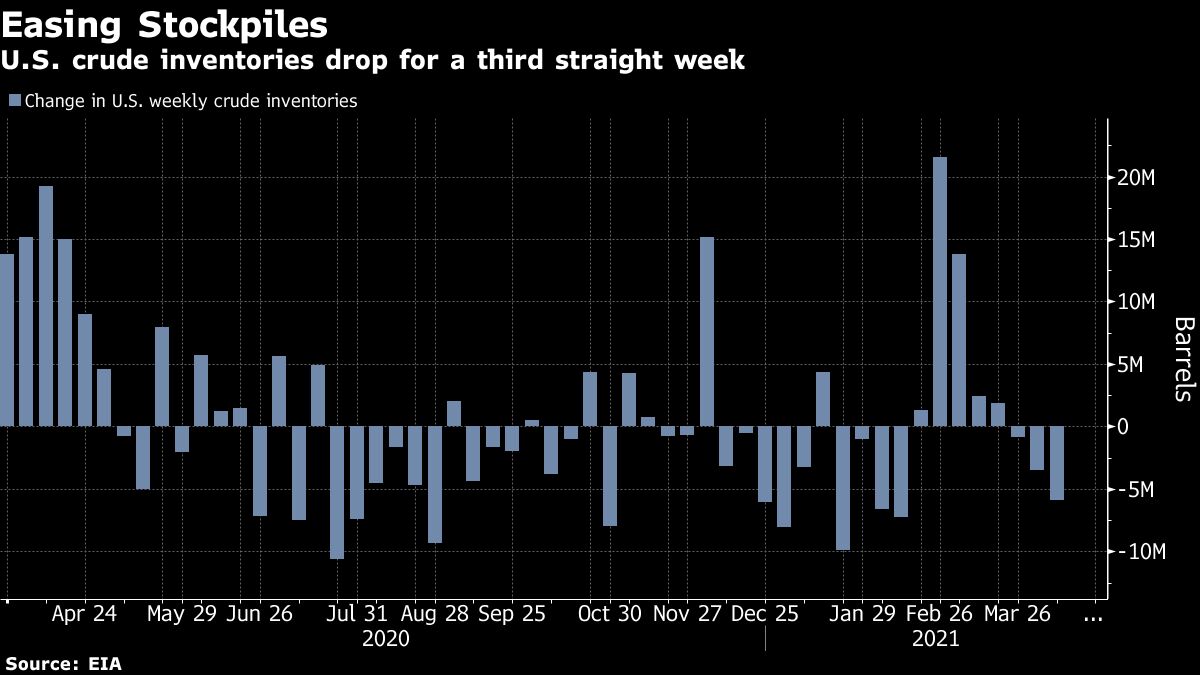
U. S. crude inventories dropped the most in almost two months last week, while a gauge of gasoline demand ticked higher for a seventh straight week.
Oil had been stuck near $60 a barrel after a rally faltered in mid-March amid a resurgence in virus cases in some regions. While the International Energy Agency sees a temporary lull in the market due to the renewed outbreaks, the organization this week followed OPEC in boosting its demand estimates for this year as the economy rebounds from the pandemic.
“The environment on the oil market remains favorable,” said Eugen Weinberg, head of commodities research at Commerzbank AG. “The picture in the oil market is continuing to brighten despite ongoing restrictions in Europe and India.”
Crude’s sharp rally has been accompanied by gains in the market’s structure that continued into Thursday.
The much-watched spread between the nearest two December contracts is on track for its strongest close since late March. That’s a sign that traders are growing more bullish on the market.
There are reasons to be cautious, however. The pandemic is raging in India, while OPEC and its allies are about to start adding more supplies. Another wild-card is Iran, which is seeking to revive a 2015 nuclear deal and have U.
S. sanctions removed to lift crude exports, but progress remains uncertain. The demand picture in Europe is also wobbly, with toll road traffic in France last week the weakest since May.
For more articles like this, please visit us at bloomberg.com
©2021 Bloomberg L. P.