
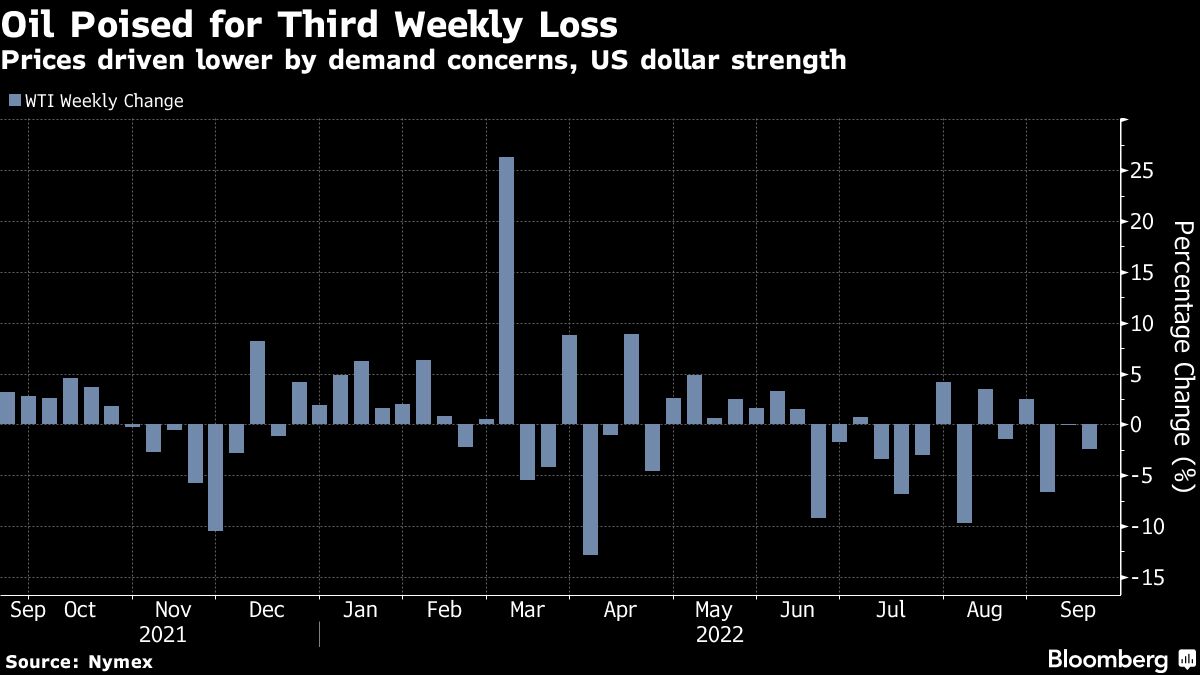
(Bloomberg) — Oil headed for a third weekly decline as a deteriorating global economy stoked demand concerns while a strong dollar made the fuel more expensive for most buyers.
West Texas Intermediate futures traded near $85 a barrel, with prices swinging in a range of less than $10 this month. Consumption is being threatened by a hawkish US Federal Reserve, the risk of a recession in Europe due to a severe energy crisis, and as China pushes ahead with its Zero-Covid policy.
Broader markets have also been weak, feeding into the bearish sentiment for oil.
Diesel prices — often correlated to the global growth outlook — have slumped this week. Chinese data on Friday painted a mixed picture in the world’s largest oil importer. While some broad indicators showed signs of recovery in August, the nation’s refining industry remained under pressure.
Traders have been looking for signs of higher export quotas for Chinese oil products this week.
“There are still concerns about the aggressive monetary tightening in Europe and the US,” said Giovanni Staunovo, commodity analyst at UBS Group AG. Those are “offset by hope that the Chinese economy improves and higher crude demand from Chinese refineries if the product export quotas are increased.”
With prices in retreat, several banks have cautioned on the outlook.
Standard Chartered Plc said the global oil market has swung into a “large surplus” this quarter, while Morgan Stanley and UBS Group AG both cut their near-term forecasts amid the recession fears.
The Bloomberg dollar gauge traded near a record this week on the outlook for tighter monetary policy. A rising greenback — which has helped push the yuan to its lowest since 2020 — makes commodities more expensive for buyers outside of the US.
Elements, Bloomberg’s daily energy and commodities newsletter, is now available.
Sign up here.
More stories like this are available on bloomberg.com
©2022 Bloomberg L. P.