
(Bloomberg) — Wall Street titan Ken Moelis’s plans to start a SPAC empire are now over, as the bubble is bursting for the struggling investment vehicles that once attracted everyone from finance heavyweights to celebrities.
The banker’s Atlas Crest Investment Corp. II said Tuesday it will seek investor approval to shut down early, returning money to shareholders and throwing in the towel on the special-purpose acquisition company.
Early Wednesday, a Moelis-backed team pulled the plug on another SPAC, marking its third withdrawn venture before going public in the past year, forgoing efforts to raise $1.2 billion among them.
It’s another sign of the bubble popping after two frenzied years in which more than 800 new SPACs were launched, including plans from Shaquille O’Neal and Martha Stewart. Indeed, Moelis joined rare company when he filed to raise three SPACs in a single day at the height of the industry’s mania in March 2021.
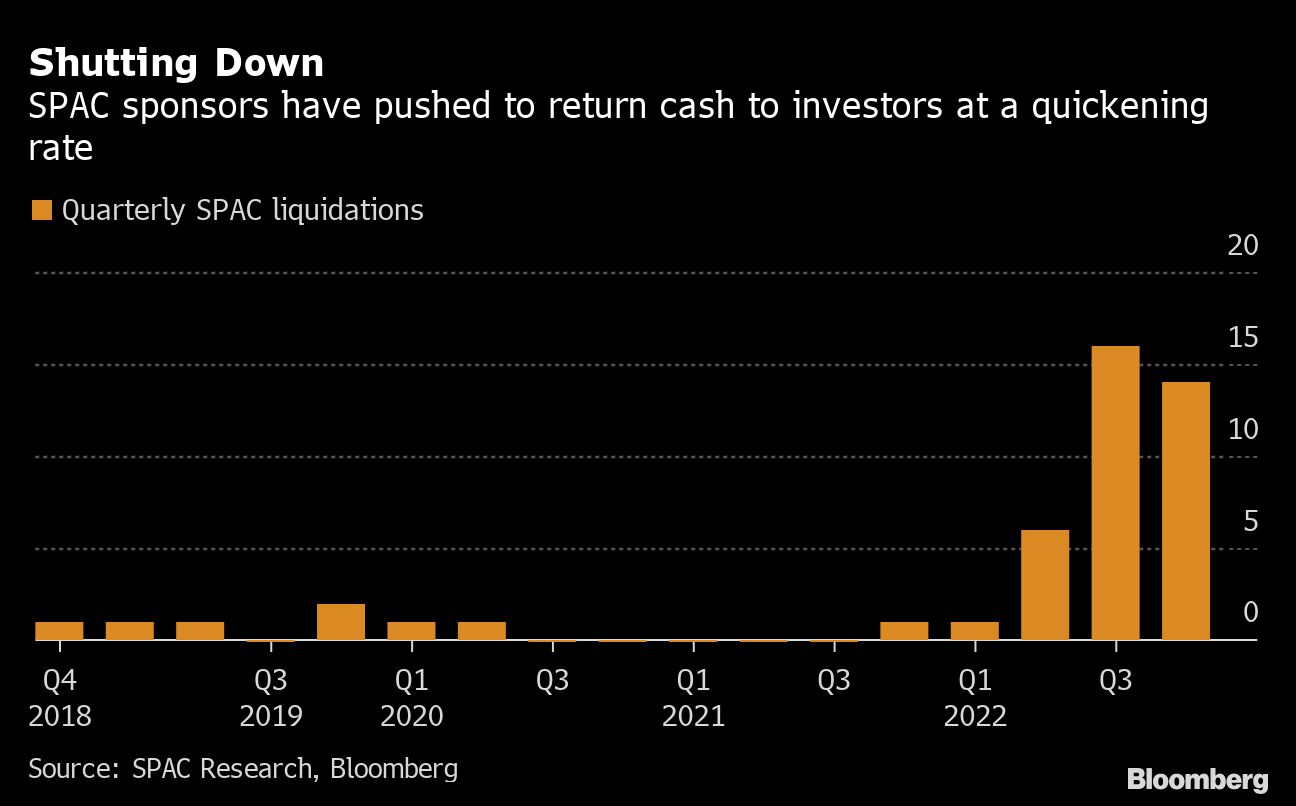
This year, 37 SPACs have shut down and returned cash, nearly four times the number over the previous five years, SPAC Research data analyzed by Bloomberg show.
Moelis is hardly alone, as “SPAC King” Chamath Palihapitiya and billionaires Bill Ackman and Sam Zell have also shuttered ventures rather than force through lackluster deals.
Atlas Crest II evaluated more than 130 companies in its quest to complete a merger before calling it quits, the SPAC said in a filing. A global market rout that includes “unconducive capital markets, an overall decline in the SPAC market and a limited pool of public company-ready business combinations interested in pursuing a business combination via a SPAC,” were to blame.
A representative for Atlas Crest II didn’t immediately respond to a phone call and email requesting comment.
The SPAC wants to shut down before the end of the year, instead of waiting for a Feb. 8 deadline.
Others have taken the same tack. Within the last 24 hours, a blank check co-sponsored by former NFL quarterback-turned activist Colin Kaepernick said it will liquidate early while one backed by RA Capital Management said it aims to shut down before 2023.
More Liquidations Coming
All told, more than 500 SPACs holding $136 billion are on the hunt for deals, racing against deadlines and each other to meet their target.
That backlog will lead to more liquidations and mergers with less-than-stellar companies, industry watchers agree.
“The capital markets are in disarray,” said Perrie Weiner, chair of the North America securities litigation group at Baker McKenzie. “What you’re seeing with the SPAC market is symptomatic to the broader markets on top of the uncertainty with the regulatory environment for SPACs.”
Moelis’s first SPAC, Atlas Crest Investment Corp. which raised $500 million in October 2020, successfully brought flying-taxi company Archer Aviation Inc. public last September.
However, the company’s stock, much like peers who have yet to generate a profit, has been hammered and is down 55% in the past year.
The fallout has been seen across the landscape for companies that went public via SPAC mergers, with riskier assets hit the hardest. The De-SPAC Index is down 70% in the past year compared with a 15% drop in the S&P 500 Index. The vast majority of de-SPACs are trading far below the $10 mark at which they typically go public.
Nearly one-third of the roughly 400 companies that merged with a SPAC in the past six years trade below $2.
Sponsors have been pushing to shut down operations early to avoid potential hits from a 1% excise tax that targets share buybacks. Atlas Crest II called out the potential liabilities as a factor in its push to liquidate early, joining at least nine other SPACs to blame the tax in the past month.
The new provision included in President Joe Biden’s Inflation Reduction Act in part makes SPACs collateral damage for the new tax, adding to other government-driven pressures.
In March, the US Securities and Exchange Commission proposed rules that would aim to treat SPACs more in-line with regular initial public offerings, requiring more disclosure and enforcing the same liability for false projections.
More stories like this are available on bloomberg.com
©2022 Bloomberg L. P.