
(Bloomberg) — Almost double-digit yields on junk-rated debt aren’t enticing to DoubleLine Capital’s Jeffrey Sherman.
While the belief that the Federal Reserve may slow down the pace of its interest-rate hikes is boosting risk assets like junk bonds, it’s premature to think that the central bank will meaningfully dial back, according to the $98 billion asset manager’s deputy chief investment officer.
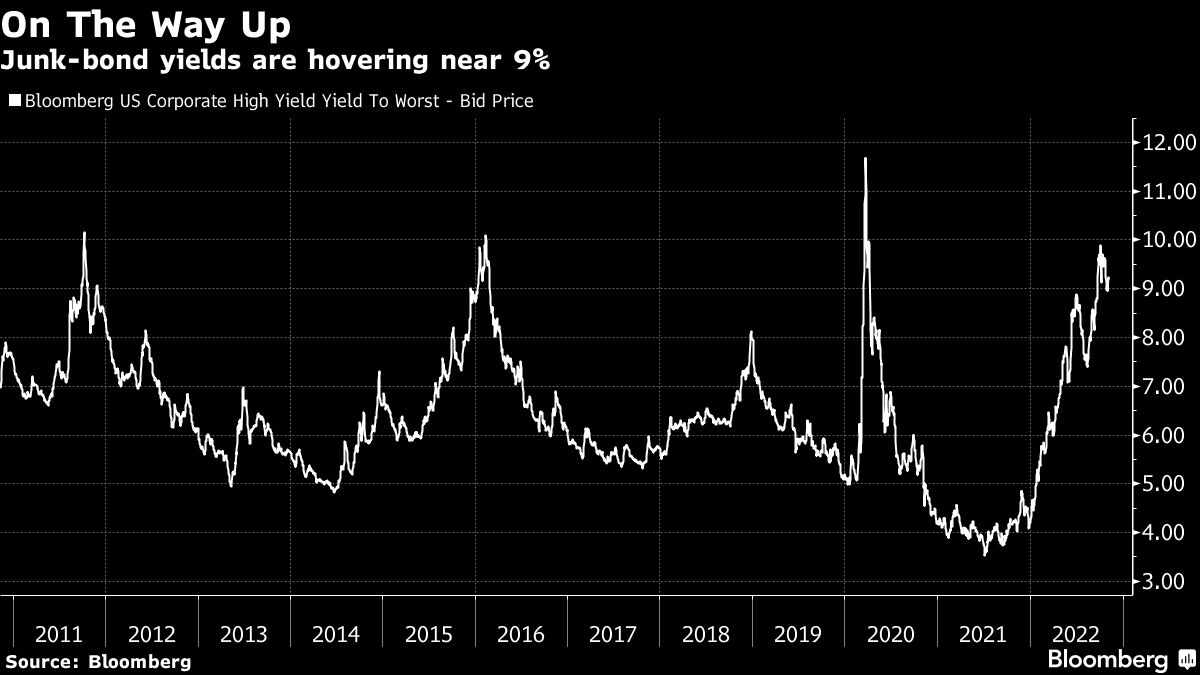
The average US junk bond yields just above 9%, outside of a pandemic-fueled spike in 2020, that’s the loftiest level since early 2016, Bloomberg data show.
“You’re talking about a 9-handle yield on junk bonds — there’s things in the investment-grade market that have similar yields,” Sherman said on Bloomberg Television’s ETF IQ on Monday. “I’m not touching high-yield today.
We think there’s been too much of this belief in a Fed pivot, the risk rally we saw in equities, so it’s looking a little rich again.”
Instead, a still-aggressive central bank combined with fears of a looming recession has Sherman favoring high-quality bonds including Treasuries, he said.
Virtually every asset class has been hammered by the Fed’s campaign this year to quell the hottest inflation in a generation.
A series of super-sized rate hikes have shredded fixed-income returns, sending yields to the highest levels in a decade.
If tempted to venture out the risk spectrum, adding high-yield debt to a portfolio should come at the expense of equities, Sherman said. The bond market has factored in the possibility of a US economic growth to a greater degree than the stock market, he said.
“When you dig down in credit quality, we think if you’re going to do that, that should be your replacement for equity today.
The downside is already priced into a lot of these markets,” Sherman said. “There can be a little bit more but if we get that pain, we get that recession, we think the equity market’s a little bit more vulnerable.”
–With assistance from Scarlet Fu.
More stories like this are available on bloomberg.com
©2022 Bloomberg L. P.